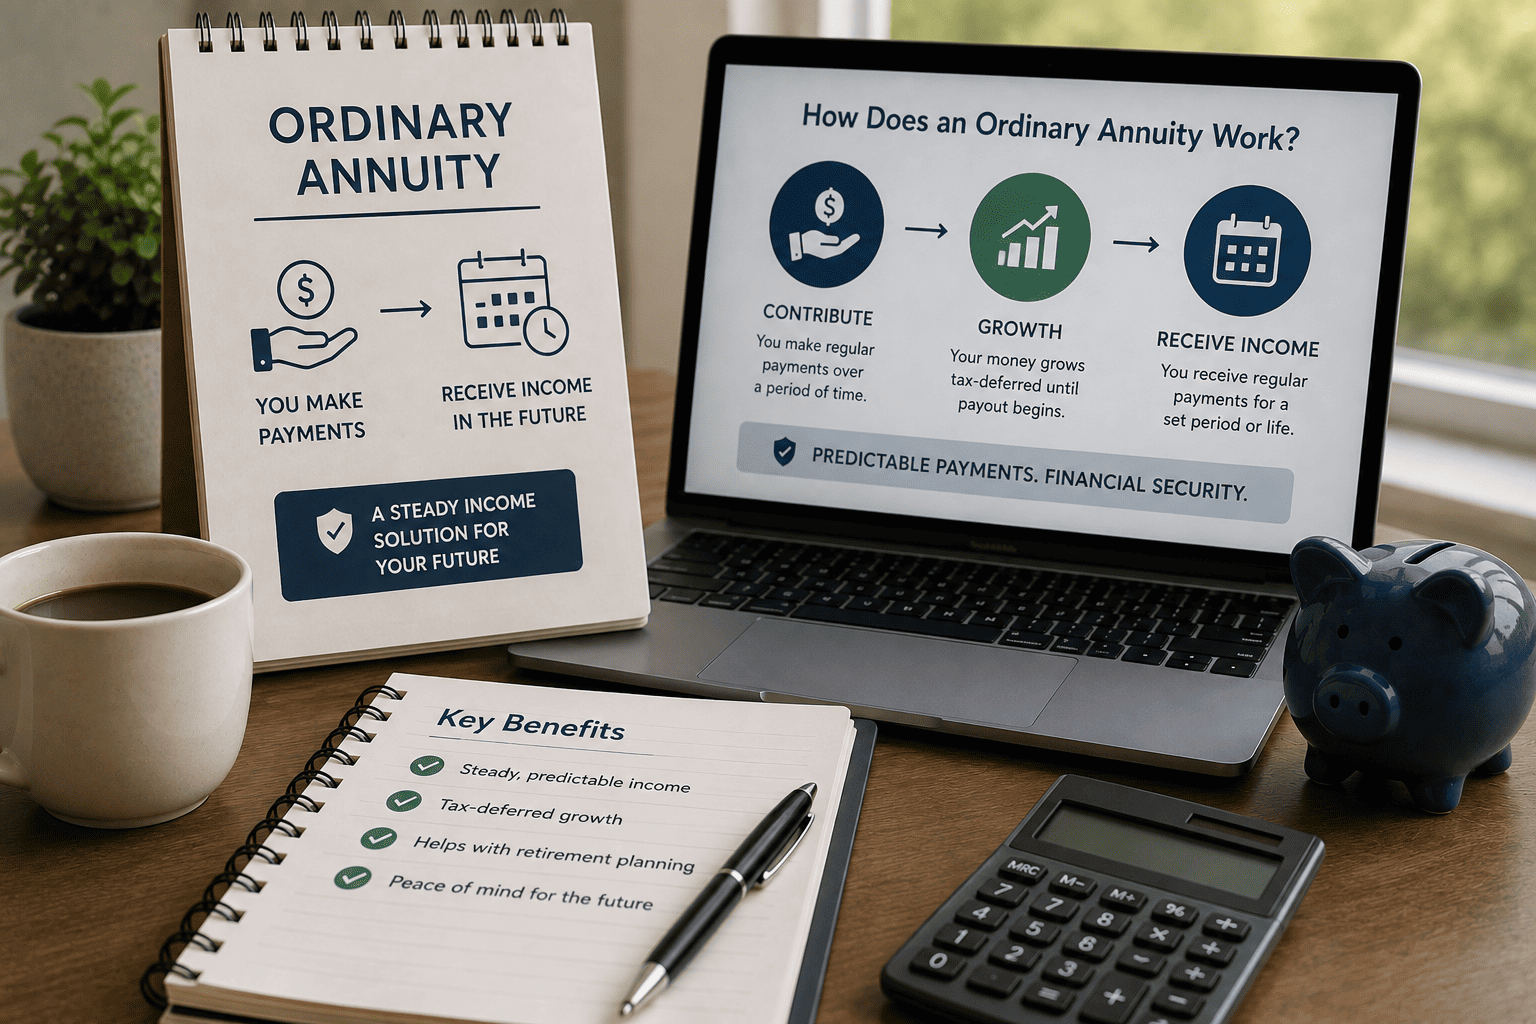
An ordinary annuity is a series of equal payments made at the end of regular intervals over a specified period. The concept is commonly used in financial calculations involving loans, investments, and retirement income.
Understanding how an ordinary annuity works can help explain how regular payments, interest rates, and time periods affect the value of a series of cash flows.
This article provides general educational information about ordinary annuities and is not individualized financial, investment, tax, or retirement advice.
An annuity is generally a series of payments made at regular intervals over a specified period.
An ordinary annuity is specifically an arrangement in which each payment occurs at the end of the payment period.
For example, if payments are made monthly, an ordinary annuity has payments at the end of each month.
Common payment schedules include:
An ordinary annuity is different from an annuity due, where payments occur at the beginning of each period.
The term “ordinary annuity” describes the timing of the payments. It should not be confused with the different types of annuity products that may be available, such as fixed or variable annuities.
An ordinary annuity involves a series of payments made at regular intervals.
For example, suppose someone makes a hypothetical payment of $500 at the end of every month for 20 years. If the applicable interest rate is 5%, the value of those payments over time can be calculated using an ordinary annuity formula.
This type of calculation illustrates how the timing of cash flows can affect their present or future value.
Actual financial products may involve additional terms, fees, taxes, investment performance, or other conditions that are not reflected in a basic ordinary annuity calculation.
Two common calculations associated with ordinary annuities are present value and future value.
Present Value
The present value formula for an ordinary annuity is:
PV = PMT × [1 − (1 + r)⁻ⁿ] / r
Where:
Future Value
The future value formula is:
FV = PMT × [(1 + r)ⁿ − 1] / r
Where:
These formulas are mathematical models. Actual financial products may use different assumptions, calculations, fees, and contractual provisions.
Ordinary annuity calculations can be useful when examining a series of retirement-related cash flows.
For example, retirement planning may involve questions about:
An actual annuity product is different from the mathematical concept of an ordinary annuity. Annuity contracts can have specific terms governing payments, fees, surrender provisions, guarantees, investment options, and other features.
The terms and conditions vary by product and provider.
When reviewing an annuity or other financial product, several characteristics may be relevant.
Regular Payments
Some annuity contracts are designed to provide payments according to the terms of the contract. The amount and duration of payments depend on the product and contract provisions.
Growth and Interest
Depending on the type of annuity, contract value may be affected by an interest rate, an index, or the performance of underlying investments.
The treatment varies by product.
Tax Treatment
Some annuity contracts may receive tax-deferred treatment under applicable tax rules. Tax treatment depends on factors such as the type of contract, ownership, contributions, withdrawals, and applicable law.
Anyone considering the tax implications of an annuity should review the applicable rules and consult an appropriately qualified tax professional.
Annuities can also involve features that consumers should understand before entering into a contract.
Liquidity
Some annuity contracts may have restrictions or charges associated with withdrawals, particularly during an applicable surrender period.
Payment Structure
The amount and timing of payments depend on the specific contract. Some products may provide fixed payments, while others may have payments or values that vary based on specified factors.
Fees and Charges
Depending on the product, an annuity may involve fees, administrative charges, investment expenses, rider costs, or surrender charges.
The applicable costs should be reviewed in the contract and related disclosures.
Investment Risk
Variable annuities generally involve investment options whose values can fluctuate based on market performance. Returns are not guaranteed unless specifically provided under applicable contract terms.
Examples of Ordinary Annuities
The ordinary annuity concept can be applied to several types of regular cash-flow calculations.
Loan Payments
Loan payments are commonly modeled as ordinary annuities when payments are made at the end of regular periods.
For example, a monthly loan payment may include both principal and interest.
Mortgage Payments
Mortgage payments can also be analyzed using ordinary annuity calculations when payments occur at regular intervals.
The calculation can help determine how payment amounts, interest rates, and loan terms relate to the present value of the loan.
Regular Savings Contributions
Regular contributions made at the end of each period can also be modeled using an ordinary annuity formula.
For example, monthly contributions to a hypothetical savings account can be used to demonstrate how the amount of each contribution, interest rate, and investment period affect future value.
The primary difference is when the payment occurs.
| Ordinary Annuity | Annuity Due |
|---|---|
| Payment occurs at the end of each period | Payment occurs at the beginning of each period |
| Common in many loan-payment calculations | Common where payments are due at the start of a period |
| Interest generally applies based on the end-of-period payment timing | Earlier payment timing can change the calculation |
Understanding payment timing is important when calculating the present or future value of a series of payments.
Annuity products can differ substantially. Before entering into a contract, consumers may want to review:
The appropriate features depend on the specific product and individual circumstances.
An ordinary annuity is a mathematical concept describing regular payments made at the end of each period. It is commonly used to calculate the present or future value of a series of cash flows.
The concept can be useful for understanding financial calculations involving loans, savings, and certain retirement-income scenarios. However, an ordinary annuity calculation should not be confused with an actual annuity contract, which may involve additional terms, costs, risks, guarantees, and tax considerations.
State Pension Resource provides educational resources about pensions and retirement-related topics and can connect state employees with independent professionals who may be able to discuss financial topics based on their licensing and expertise.
This article is for educational purposes only and does not constitute individualized financial, investment, tax, retirement, or legal advice. Financial products and retirement rules vary by individual circumstances and applicable laws. Review official documents and consider consulting appropriately qualified professionals before making financial decisions.